A payment institution with hardware, not a current-account bank
myPOS sells card machines and a merchant wallet to small businesses that need to take Visa, Mastercard, Maestro, American Express, Apple Pay, and Google Pay without waiting weeks for a classic acquiring contract. The legal wrapper matters more than the plastic terminal. Payments and e-money in the EEA are provided by myPOS Limited, a private limited company registered in Ireland (company number 700880) with a registered office at 12 Stephen's Green, Dublin 2. It is authorised as an electronic money institution under the European Communities (Electronic Money) Regulations 2011, licence C475122, granted by the Central Bank of Ireland on 16 September 2022. That licence covers issuing and redeeming e-money, executing payment transactions on an account that is not a credit line, and issuing payment instruments or acquiring card transactions. It does not turn myPOS into a bank that can lend your float or protect balances under a national deposit-guarantee scheme the way a Belgian, Dutch, or German credit institution would.
The product idea dates to 2012, when EU payment rules opened space for non-bank acquirers. The company presented the platform at Mobile World Congress in Barcelona in 2014 as a way to pay merchants immediately instead of holding card proceeds for days. Operations grew out of Varna, Bulgaria. A London headquarters followed in 2017, along with flagship stores; the firm now cites more than fifteen stores and more than 400,000 merchants across more than thirty countries. Public awards include Best Financial Services 2025 at the Global FinTech Awards and Best Business Payments System 2024 at the PayTech Awards. Trophies do not replace the fee table, the safeguarding wording, or merchant-category underwriting.
Terminals that work without a phone dongle
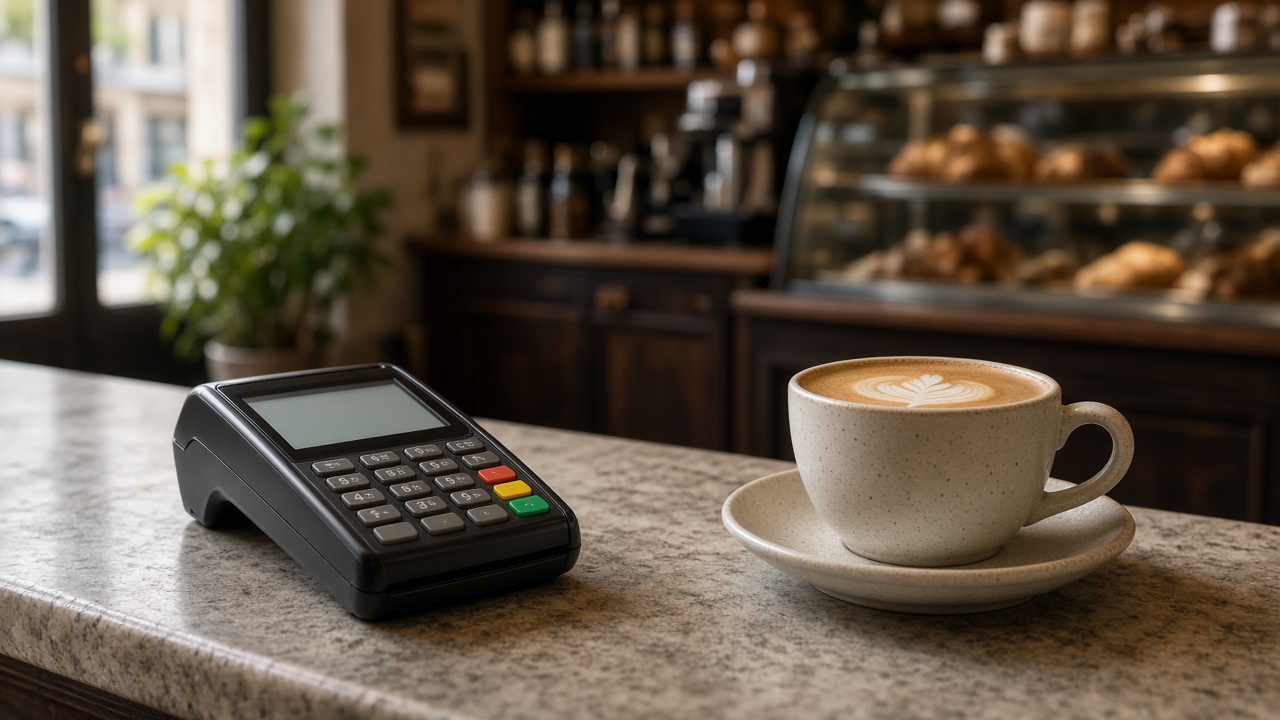
Standalone hardware is the main pitch versus clip-on readers that die when a smartphone loses signal. Catalogue models include myPOS Go 2, a compact standalone reader; myPOS Flex, a small smart terminal for counter or handheld use; and myPOS Ultra, an Android terminal with a high-speed printer. SoftPOS options such as myPOS Glass let a compatible phone take contactless payments without a second gadget. Dedicated machines are described as autonomous: they do not need to pair with a phone to authorise a sale. Each terminal ships with a pre-installed data SIM for 3G or 4G plus Wi-Fi. Go 2 notes specify 2.4 GHz Wi-Fi, so a dual-band router is not a reason to assume 5 GHz will work. Offline mode on Go 2 stores transactions locally and syncs when the radio returns; useful on a stall, risky if you treat an unconfirmed sale as cash.
Supported methods include magstripe, Chip and PIN, and NFC wallets. Receipts can go out as SMS or email; Ultra adds thermal paper. Portable-unit software lists payment request, pre-authorisation, refund, last-transaction void, tipping, and prepaid top-up. Hardware prices sit on the live country shop and move with promotions and rental, so this review does not freeze a euro or pound figure. You can order a machine before you have an account, but you cannot take live cards until the merchant account is verified. Activation, per the public FAQ, is: create the free account in the app, complete online identification with a valid passport or driving licence (copies are not accepted), wait for review, then pair the terminal and the complimentary business debit card.
- EEA e-money services from myPOS Limited (EMI, Central Bank of Ireland, licence C475122), not a credit institution
- Standalone Go 2, Flex, and Ultra terminals plus phone tap-to-pay via myPOS Glass
- Free data SIM and Wi-Fi on dedicated machines so a counter broadband line is optional
- Instant settlement of card takings into a multi-currency e-money account with an IE IBAN
- Online checkout, payment links, QR codes, and a mail-order/telephone-order virtual terminal
- Complimentary business Mastercard for spending accepted funds, addable to Apple Pay and Google Pay
The free account, IBANs, and where the money actually sits
The merchant account is advertised as free of setup fees, monthly service fees, and long-term contracts. Costs are meant to appear when a payment succeeds: a percentage that varies by method, plus a small fixed fee. Public UK-facing pages have shown an example of 1.10 percent plus a few pence, with a note that the mix changes by method. Treat that example as a pointer, not a contract. You receive a multi-currency e-money account. Irish pages describe an IE IBAN and balances in a dozen currencies, including GBP and CHF. You can move money between wallets, send instant transfers to other myPOS users, and pay suppliers by SEPA instant or SWIFT. Statements export as PDF, Excel, CSV, or MT940. Multiple users can sit on one merchant with different permissions. None of this is a loan, a savings product, or an investment account. This article is not investment advice.
Safeguarding is the sentence most merchants skip. myPOS says client money sits in designated segregated accounts at eligible banks approved by regulators, held so those funds cannot be used for lending or proprietary investment. That structure is the EMI version of ring-fencing. It is not the same as a Belgian or German deposit-guarantee sticker on a current account. If you need statutory deposit insurance, keep a conventional business bank account and treat myPOS as a payments rail that you sweep. Instant settlement is the operational reason to use the rail: the company claims card payments hit the myPOS balance in about three seconds with no extra payout fee into that wallet. From there you spend on the free Mastercard, transfer out, or leave a working float. ATM withdrawals worldwide are listed among extra services; fees for those cash-outs belong on the current tariff, not in a reviewer’s memory.
Open the current European catalogue, read the fee table for your MCC, and only then pick Go 2, Flex, Ultra, or a rental plan.
Compare myPOS terminals and account terms →Online checkout when there is no counter
A stall that later grows a web shop does not have to add a second acquirer. myPOS Online and Checkout cover a hosted payment page or a shopping-cart plugin. Payment links and PayButtons are for invoices and social-media sales without a full storefront. Payment tags and QR codes sit in the same family. The MO/TO virtual terminal is for keyed-in cards from email or phone, a different risk profile from a chip at the counter; expect tighter fraud monitoring. AppMarket, developer acquiring, and affiliate programmes are optional side doors. The core job remains: accept a card, settle fast, spend or sweep.
Onboarding is still KYC. Eligibility copy on Irish pages talks about self-employed people, sole traders, limited companies, and LLPs registered with Companies House, which is UK-shaped language on a pan-EU product; your local signup flow will ask for the documents that match your legal form. Identification runs in the mobile app over a live camera session. Review time depends on how complete the file is and what you sell. High-risk merchant category codes get delayed or declined at every EMI, not only this one. Keep a conventional bank account in your own name for tax, wages, and anything a supplier will not accept from an e-money IBAN. Some landlords, utilities, and public bodies still reject EMI IBANs. That friction is a feature of the licence type, not a bug in the app.
myPOS is a regulated e-money wallet with decent standalone terminals and a three-second payout story. It is not a bank, not deposit-insured in the classic sense, and not a reason to skip a proper fee comparison against other EU acquirers.
— Marcus Chen
Who should buy a terminal here, and who should stay with a bank acquirer
This setup fits market traders, food trucks, mobile hairdressers, pop-up retail, and small web shops that want one wallet for face-to-face and remote cards. Instant access to takings is the practical advantage when cash-flow is the constraint, not when you need an overdraft. Skip it if you require a full business current account, local direct-debit origination as a bank, or statutory deposit protection on the entire float. Skip it if your mix is delayed fulfilment and chargebacks you cannot staff. Skip it if you thought the free account meant free acquiring; every successful card still prices a percentage plus a fixed slice. A high-street bank acquirer can still win on blended rates at volume. myPOS wins when you want hardware that includes connectivity, a same-day wallet, and no monthly retainer while you are closed.
- Read the live pricing page for your country site and card mix before you order hardware
- Complete KYC with original photo ID in the app; photocopies stall verification
- Keep a traditional bank account for payroll, tax, and payees that reject EMI IBANs
- Sweep large balances if you want deposit-guarantee coverage rather than EMI safeguarding only
- Test Wi-Fi versus the included SIM on the actual stall, not only in the kitchen
- Treat offline mode as a backup, not as a promise that every stored sale will later clear
FAQ: banks, payouts, cards, and contracts
Is myPOS a bank?
No. It is an electronic money institution. The Dublin entity can issue e-money and acquire payments under Irish authorisation passportable across the EEA. It cannot take deposits as a credit institution and it does not run a classic lending book with your merchant float. Marketing language that calls the product a business account is describing an e-money wallet with IBANs and cards, not a full bank relationship. If a supplier asks whether you bank with myPOS, the accurate answer is that you hold e-money with a payment institution.
How fast do card payments arrive?
myPOS states that authorised card payments land in the merchant account in a few seconds, with a public figure of three seconds and no extra charge for that internal settlement. That clock starts after authorisation, not after a customer disputes a sale. Transfers from the wallet to an external bank follow SEPA or SWIFT timings and any tariff in force. Instant inside myPOS is not the same as instant to your salary account at another bank.
Do I pay a monthly fee for the account?
The published account story is no setup fee, no monthly service fee, and no binding term on the wallet itself. You pay when you accept a payment, and you may pay for extras such as extra cards, ATM cash, or a terminal rental. Hardware has a purchase or rental price on the shop. Always open the current tariff for your country rather than assuming last year’s screenshot still applies.
Which cards and wallets does a terminal take?
Public hardware pages list Visa, Mastercard, Maestro, American Express, contactless, Apple Pay, Google Pay, and other NFC wallets, plus magstripe where that still appears. Scheme coverage can still vary by merchant category and by country. If American Express or a local debit scheme is essential to your ticket size, confirm it on the live product page and in the contract, not in a banner.
Can I accept payments without a website?
Yes. Payment links, QR codes, and the virtual terminal are built for that. A physical terminal still needs the verified account. A phone-only Glass flow still needs the same KYC. Remote card entry increases fraud and chargeback exposure compared with a chip on the counter, so keep order records.
Create the free account, finish identification, and compare terminal purchase against rental using the fee page for your sales mix.
Start a myPOS merchant check →Bottom line
myPOS.eu is a serious SME payments stack: Irish EMI licence, standalone terminals with included data, a multi-currency wallet, and settlement measured in seconds. It is the wrong mental model if you wanted a bank, a credit line, or deposit insurance on every euro you leave overnight. Use it as a till and a sweep account, read the tariff, and keep a real bank for everything the licence cannot do.